Car insurance has a funny way of making your wallet feel lighter without actually giving you anything to show for it. You pay every month, drive carefully, avoid trouble, and still get a renewal quote that looks like your car has been secretly entering Formula 1 races.
The good news? You don’t always have to accept the first insurance price you’re offered.
From comparing quotes and adjusting your coverage to improving your driving habits and taking advantage of available discounts, there are several practical ways to reduce your car insurance costs without leaving yourself dangerously underinsured.
In this guide, we’ll explore how to save money on car insurance, what factors affect your premium, mistakes that can make insurance more expensive, and simple strategies that could help keep more money in your bank account.
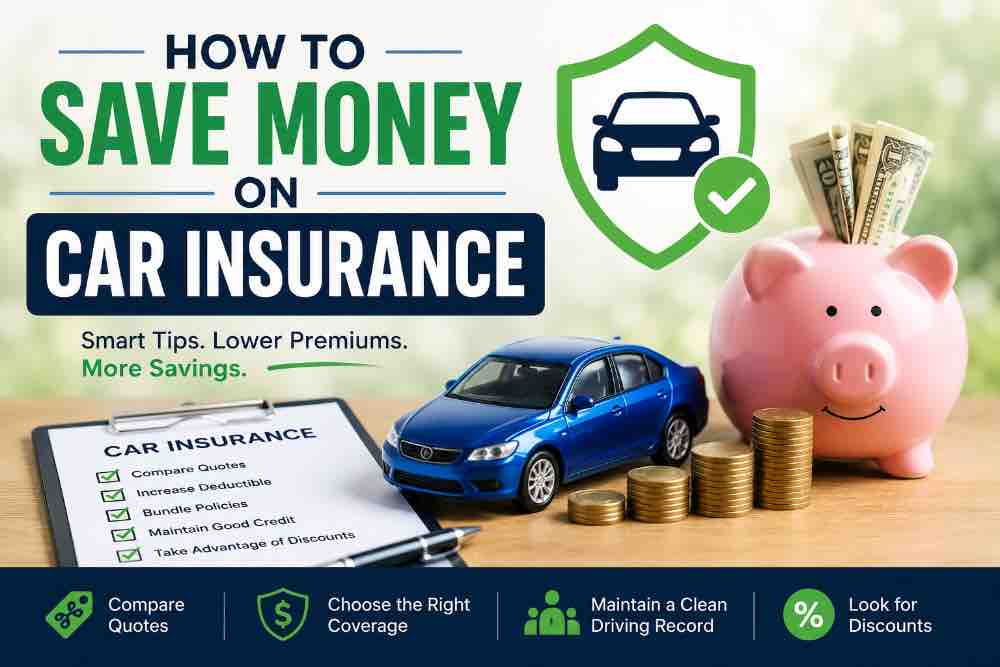
How to Save Money on Car Insurance: 15 Smart Ways to Cut Your Premium
1. Shop Around and Compare Car Insurance Quotes
One of the easiest ways to potentially save money is to compare quotes from multiple insurers.
Insurance companies calculate risk differently, so two providers can look at the same driver, same vehicle, and same address and come up with surprisingly different prices.
Don’t assume your current insurer is automatically giving you the best deal just because you’ve been loyal for years.
Loyalty is great in relationships. With insurance, comparison shopping can sometimes be more rewarding.
When comparing quotes, make sure you’re comparing similar:
- Coverage limits
- Deductibles or excess
- Optional coverage
- Add-ons
- Benefits and exclusions
The cheapest quote isn’t necessarily the best deal if it leaves you with inadequate coverage.
2. Increase Your Deductible or Excess
If your policy allows it, choosing a higher deductible or excess can reduce your regular premium.
For example, you might choose to pay more yourself when making a claim in exchange for a lower insurance premium.
However, don’t increase it to an amount you couldn’t realistically afford after an accident.
A lower monthly bill isn’t much fun if your emergency fund starts crying the moment you need to make a claim.
3. Ask About Every Available Discount
Insurance companies may offer discounts based on factors such as:
- Safe driving
- Multiple vehicles
- Bundling policies
- Low annual mileage
- Security features
- Paying annually
- Memberships or professional affiliations
- Driver training
- Telematics or usage-based insurance
Discounts vary between insurers, so don’t be shy about asking.
A simple question such as “What discounts am I eligible for?” could uncover savings you didn’t know existed.
4. Drive Less If You Can
Your mileage can influence how much you pay for insurance.
Generally, spending less time on the road can mean fewer opportunities for an accident and it’s one of our recommended ways to save money on gas bills.
If you can combine errands, work remotely occasionally, carpool, walk short distances, or use public transportation when practical, you may be able to reduce your annual mileage.
Just make sure you report your mileage accurately. Saving money isn’t worth creating problems with your policy later.
5. Maintain a Clean Driving Record
Speeding tickets, accidents, and other driving violations can make insurance more expensive.
The simplest strategy is also the least exciting:
Drive safely.
Avoid unnecessary speeding, aggressive driving, distracted driving, and other risky behavior.
Your future insurance premium may thank you.
6. Consider a Usage-Based Insurance Program
Some insurers offer programs that use telematics technology to assess driving behavior.
Depending on the insurer and program, factors such as braking, acceleration, mileage, and driving times may be monitored.
If you’re a consistently safe driver, this could potentially help you qualify for a lower premium.
But read the terms carefully before signing up. Understand what information is collected, how it is used, and what happens if your driving score isn’t as impressive as you expected.
7. Choose Your Car Carefully
The car you drive can have a significant effect on insurance costs.
Vehicles with expensive repairs, high theft rates, powerful engines, or costly replacement parts can sometimes cost more to insure.
If you’re shopping for a vehicle and insurance costs matter to your budget, get insurance quotes before buying the car.
This prevents the classic mistake of buying the dream car first and discovering later that the insurance bill has its own mortgage.
8. Improve Your Vehicle’s Security
Depending on your insurer and location, security features may affect your insurance costs.
Features such as approved alarms, immobilizers, tracking devices, or secure parking may help reduce risk.
Before spending money on an aftermarket security device specifically for an insurance discount, check with your insurer to confirm whether it qualifies.
Otherwise, you could spend $300 to save $20 and accidentally turn your “money-saving strategy” into an expensive hobby.
9. Bundle Your Insurance Policies
If you have multiple insurance policies, such as home, renters, or other vehicle insurance, ask whether your insurer offers a multi-policy discount.
Bundling can sometimes make your overall insurance costs lower and may also simplify your payments.
However, don’t assume bundling is automatically cheaper. Compare the total cost against buying each policy separately.
10. Review Your Coverage Regularly
Your insurance needs can change over time.
Perhaps your car is older, you drive less, you’ve moved, your circumstances have changed, or you no longer need certain optional extras.
Review your policy at least once a year and ask:
- Do I still need every optional coverage?
- Has my annual mileage changed?
- Is my vehicle still worth the same amount?
- Have I become eligible for new discounts?
- Can another insurer provide comparable coverage for less?
Don’t cancel important coverage simply to reduce the premium. The goal is to remove unnecessary costs, not necessary protection.
11. Avoid Unnecessary Add-Ons
Insurance policies can come with plenty of optional extras.
Some may be valuable to you. Others may duplicate coverage you already have elsewhere.
Before paying for an add-on, ask:
“Would I actually use this?”
If the answer is no, removing it could reduce your premium.
Just make sure you understand what you’re giving up before removing anything.
12. Pay Your Premium in the Most Cost-Effective Way
Depending on the insurer, paying your premium annually rather than monthly may reduce the overall cost because some providers charge additional fees for installment payments.
Don’t assume this is always the case.
Ask your insurer for the total annual cost under different payment options.
Sometimes the difference is meaningful; sometimes it isn’t.
13. Keep Your Insurance Information Accurate
Make sure your insurer has accurate information about:
- Your address
- Vehicle usage
- Annual mileage
- Drivers
- Parking arrangements
- Vehicle modifications
- Driving history
Providing inaccurate information to obtain a cheaper premium can cause serious problems when you need to make a claim.
The best savings strategy is one that doesn’t come back to bite you later.
14. Don’t Automatically Renew Your Policy
Automatic renewal is convenient, but convenience can become expensive.
When your renewal notice arrives, treat it as an invitation to shop around.
Get several quotes and compare them with your renewal price.
If another insurer offers comparable coverage at a lower price, you can decide whether switching makes sense.
You can also ask your current insurer whether they can match or improve the price.
Sometimes all it takes is asking.
15. Build a Better Overall Financial Safety Net
Car insurance is only one part of your driving budget.
Saving money becomes easier when you also maintain an emergency fund for unexpected costs such as repairs, deductibles, or excess payments.
That way, you’re less likely to choose dangerously low coverage simply because you need to keep your monthly expenses down.
The goal isn’t to make insurance disappear.
The goal is to pay a reasonable price for the protection you actually need.
Remember: Saving money on insurance is only one part of reducing your monthly expenses. If you’re trying to get better control of your entire financial life, our guide on how to make a budget as a beginner can help you organize your income, bills, savings, and spending in one place.
How Much Can You Save on Car Insurance?
There isn’t one universal amount because insurance prices depend on factors such as your location, age, driving history, vehicle, coverage, mileage, and insurer.
But even small reductions can add up.
For example, saving $20 per month means:
- $20 × 12 = $240 per year
Saving $50 per month means:
- $50 × 12 = $600 per year
That’s money that could instead go toward your emergency fund, car maintenance, debt repayment, groceries, or something considerably more enjoyable than an insurance renewal email.
Once you’ve reduced your insurance costs, look for other ways to stretch your shopping budget. Our cashback explained guide covers how cashback works and how you can potentially earn money back on everyday purchases.
Common Mistakes That Make Car Insurance More Expensive
Watch out for these mistakes:
- Accepting the first quote
- Automatically renewing every year
- Forgetting to ask about discounts
- Choosing unnecessary add-ons
- Reporting inaccurate information
- Ignoring your annual mileage
- Buying a car without checking insurance costs first
- Choosing a deductible you can’t afford
- Canceling useful coverage just to save a few dollars
- Focusing only on price instead of comparing the full policy
Note: If your insurance bill is competing with groceries and other essential expenses, check out our guide on how to save money on a low income for practical ways to reduce everyday spending without making life miserable.
How to Save Money on Car Insurance Without Being Underinsured
The cheapest insurance policy isn’t always the best policy.
Before switching, compare the actual protection you’re receiving.
Look at:
- Coverage limits
- Deductibles or excess
- Collision or comprehensive coverage where applicable
- Liability protection
- Exclusions
- Rental or replacement vehicle benefits
- Roadside assistance
- Claim conditions
- Optional extras
A policy that’s $30 cheaper per month isn’t necessarily a bargain if it provides significantly less protection.
Frequently Asked Questions About Saving Money on Car Insurance
What is the easiest way to lower car insurance?
Start by comparing quotes from several insurers and asking your current provider about available discounts. Then review your coverage and deductible to see whether adjustments make sense.
Does shopping around really save money on car insurance?
It can. Insurers use different pricing models, so comparing multiple providers can reveal significant differences in premiums for similar coverage.
Is it cheaper to pay car insurance annually?
It can be, depending on the insurer. Some companies charge less overall when customers pay annually, while others offer different payment options. Always compare the total cost.
Does a higher deductible lower insurance premiums?
Often, yes. A higher deductible can reduce your premium, but you’ll have to pay more out of pocket if you make a covered claim.
Can improving my credit lower car insurance?
In some locations, insurers may consider credit-based insurance information when pricing policies, while other jurisdictions restrict or prohibit this practice. Check the rules where you live.
Should I cancel comprehensive or optional coverage to save money?
Not automatically. Removing coverage can lower your premium but could leave you exposed to significant financial losses. Consider your vehicle’s value, financial situation, and risk before making changes.
How often should I compare car insurance?
A good habit is to compare prices around renewal time and whenever something significant changes, such as your vehicle, address, mileage, or driving circumstances.
Final Thoughts: Make Your Insurance Work for Your Budget
Learning how to save money on car insurance doesn’t require becoming an insurance expert or spending your weekend reading policy documents with a magnifying glass.
Start with the basics: compare quotes, ask about discounts, review your coverage, maintain a clean driving record, and make sure you’re only paying for protection you actually need.
Most importantly, don’t sacrifice essential coverage just to get the cheapest possible premium.
The winning strategy is simple: pay less where you can, stay properly protected, and put the money you save toward something more exciting than another insurance bill.
Smart insurance shopping means finding the best value—not simply the lowest number on the screen.